What’s a Good Checklist to Run Before Hurricane Season for Valuables?
When you live in Florida, getting ready for hurricane season isn’t only about shutters, batteries, and bottled water. It’s also about knowing what you own, where the records are, what your insurance actually covers, and how you would access cash if normal banking and repair services slow down after a storm.
That preparation matters especially for valuables such as jewelry, watches, art, collectibles, and important documents. A well-organized inventory can make an insurance claim easier to support. Reviewing your coverage can reveal limits before you need them. And thinking through liquidity in advance may help you avoid making rushed decisions when contractors, banks, and lenders are dealing with the same emergency.
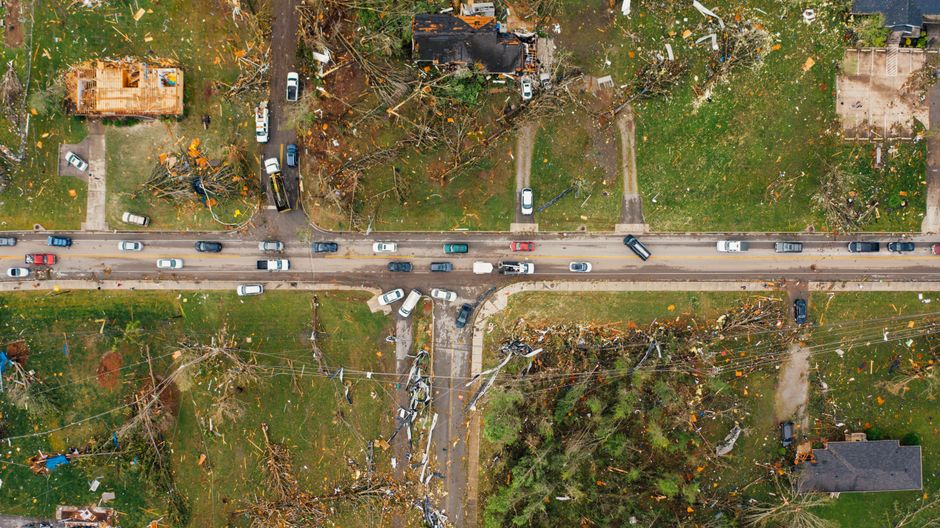
Use this checklist before the season begins—and revisit it when you buy, sell, or substantially change a valuable item.
1. Check Your Hurricane Deductible and Cash Exposure
Florida hurricane deductibles are usually percentage-based, rather than a simple fixed dollar You can find out more amount. The percentage generally applies to the insured dwelling limit, but your policy’s wording and deductible rules determine the actual calculation. Don’t assume the number is based on the amount of damage or the value of your belongings.
For example, if a home has a $500,000 dwelling limit, common hurricane deductible options of 2%, 5%, and 10% would work out to:
Hurricane deductible Example calculation on $500,000 dwelling limit Illustrative deductible 2% $500,000 × 0.02 $10,000 5% $500,000 × 0.05 $25,000 10% $500,000 × 0.10 $50,000That deductible can create a five-figure cash gap before insurance contributes to a covered loss. The deductible is separate from questions about whether a particular item or type of damage is covered. A damaged watch, for instance, isn’t automatically paid for simply because the house sustained hurricane damage. Coverage depends on your policy, the cause of loss, exclusions, limits, and how the item is insured.
- Find the hurricane deductible on your declarations page and read how it is triggered.
- Ask your insurer or agent to explain which dwelling limit is used in the calculation.
- Check whether your policy has separate deductibles for other types of loss.
- Decide where deductible money could come from without relying on a new loan after a storm.
Keep in mind that a percentage deductible is not the same as a savings recommendation. The right emergency reserve depends on your household, policy, and other available resources. The important step is knowing the number before hurricane warnings begin.
2. Inventory Valuables Before You Need to Prove What You Own
Memory is a poor inventory system, particularly after a stressful loss. Make a current list of valuable property and store it somewhere you can reach if your home is inaccessible. Include items that are easy to overlook: inherited jewelry, watches, musical instruments, collections, artwork, designer accessories, and important electronics.
For each item, record:
- Brand, model, description, and identifying features.
- Serial number, reference number, or other unique identifier, if available.
- Purchase date, seller, and approximate purchase price.
- Current location and any identifying marks or modifications.
- Appraisal, receipt, warranty, service record, or provenance document.
- Whether the item is insured individually, subject to a special limit, or not listed on the policy.
Take clear photos and short videos. Photograph each item from multiple angles, including close-ups of serial numbers and distinctive details. A slow video walkthrough of the home can also show where property is normally kept. Avoid posting images of valuables, serial numbers, or security arrangements publicly.
Put your records in more than one place. Keep a copy outside the home, such as with a trusted relative or in a secure digital account. Store cloud backups behind a strong, unique password and multifactor authentication. Encrypt sensitive files where practical, and keep a separate note explaining how an authorized family member can access the records if you cannot.
3. Review Jewelry and Watch Coverage—Not Just the Policy Summary
Standard homeowners policies may limit how much they pay for certain categories of property, including jewelry, watches, and other high-value items. Limits can apply to specific causes of loss, and a general contents limit may not be enough for a collection. Ask your insurer to explain the relevant limits, exclusions, deductibles, and documentation requirements.
If an item would be expensive to replace, ask whether you should schedule jewelry coverage or schedule the watch separately. Scheduled coverage typically means listing an item and its agreed or appraised value under an endorsement or separate policy. The terms vary, so confirm exactly what is covered, where it applies, and whether accidental loss, theft, or damage is included. Do not assume every policy treats hurricane-related damage, flooding, and wind damage the same way.
Before scheduling an item
- Get a current appraisal if the insurer requires one or if the existing valuation is out of date.
- Confirm whether the insurer wants an appraisal, sales receipt, or both.
- Check how often the insurer expects values to be updated.
- Ask about coverage while traveling, wearing the item, or leaving it with a repair professional.
- Keep the policy endorsement with your inventory and verify the listed description and value.
For watches, a market tracker can be useful context, but it is not the same as an insurance appraisal or guaranteed resale offer. WatchCharts, for example, provides secondary market pricing data that can help you follow price trends for supported models. Use that information as a reference point, then ask your insurer what valuation method it accepts. Condition, box and papers, service history, model variation, and the actual market at the time of sale can all affect value.
4. Make Important Records Available Outside the House
Good documentation has little value if it is trapped in a home you cannot enter or on a device that was damaged. Build a simple digital records folder and test that you can access it from another device.
- Scan or photograph policies, declarations pages, appraisals, receipts, and service records.
- Save original files where possible and use clear filenames, such as “Watch—Brand—Reference—Appraisal—2026.”
- Make cloud backups and a second backup on an encrypted drive stored off-site.
- Keep your insurer’s claims number, agent contact, and policy number in an accessible format.
- Share access instructions with a trusted person, while protecting passwords and financial information.
- Test the backup by opening a few files on a phone or computer other than your primary device.
Cloud backups are convenient, but account security matters. Use multifactor authentication, avoid reusing passwords, and review who has access to shared folders. A backup should help you recover records—not expose sensitive details about what you own or where you keep it.
5. Plan for Cash When Normal Options May Be Slow
After a major storm, post-storm liquidity can be constrained just when families need to pay for temporary lodging, transport, cleanup, repairs, or an insurance deductible. Banks may have limited hours or roof damage deductible florida disrupted services. Contractors may require deposits and face long backlogs. Even when a lender remains open, a new application can take time to process.
Do not count on opening a HELOC or getting new credit after a disaster. Lenders may pause applications, change requirements, or delay access to funds in affected areas. Your property condition, income disruption, documentation, and the lender’s procedures may also affect timing. A credit line already in place can still have terms and conditions that matter, so understand them in advance.
Consider a practical liquidity plan that does not depend on a single source. It might include an emergency savings reserve, a payment method that works if one bank is unavailable, and a clear list of essential bills. Keep only a reasonable amount of cash on hand, since cash can be lost or stolen and may not be usable if businesses cannot operate.

For some owners, a collateral loan—where a watch is held as security—may be one possible source of funds to evaluate. Diamond Banc, for example, is a company that offers loans secured by luxury assets. Before considering any such arrangement, compare the interest rate, fees, loan-to-value amount, repayment schedule, insurance and custody terms, and what happens if you cannot repay on time. A collateral loan is not a substitute for insurance, and using a valuable item as security means it may be held by the lender during the loan.
Some households also work with a financial adviser, such as Morgan Stanley, as part of broader planning for cash reserves and financial accounts. The right approach depends on your situation; focus on understanding access, timing, costs, and risks rather than assuming any provider or product will be available immediately after a storm.
6. Secure Valuables and Know What You’ll Take
Make a plan for what happens as a storm approaches. Follow official evacuation orders and do not risk personal safety to retrieve belongings. If there is time and it is safe, move small, high-value items and essential records to a secure location away from expected exposure. Use a safe that is appropriate for the hazard, but remember that no safe is automatically floodproof or hurricane-proof.
- Choose a few items and documents you would take if you had to leave quickly.
- Store that list with your evacuation plan, not only on a device inside the house.
- Know how to protect valuables from water, wind, and theft without delaying evacuation.
- Record the condition of items before the season and update photos after purchases or repairs.
- Keep serial numbers and proof of ownership separate from the valuables themselves.
Don’t move property into a risky location just to keep it close. If you use a bank safe-deposit box or another storage service, check access hours, location, contract terms, and whether the arrangement fits your needs. A box may not be accessible during a closure or evacuation, so keep essential documents and backup records elsewhere too.
7. A Simple Pre-Season Checklist
- Read the declarations page and calculate the dollar amount of the hurricane deductible.
- Review contents limits, exclusions, and special limits for jewelry, watches, and collections.
- Ask whether to schedule jewelry coverage for high-value pieces.
- Update appraisals and confirm that listed descriptions and values are accurate.
- Take photos and videos; record photos and serial numbers in a secure inventory.
- Create cloud backups and an off-site backup of essential records.
- Check your emergency cash plan and avoid relying on post-disaster credit approval.
- Review any existing credit line or collateral-loan terms before you need funds.
- Make a safe evacuation plan for people, pets, valuables, and essential documents.
- Set a calendar reminder to review the inventory and coverage once a year.
Prepare the Paperwork Before the Forecast Turns
A hurricane checklist for valuables is really a checklist for choices you want to make calmly. Know how your deductible is calculated, document what you own, confirm whether your coverage matches the value of your belongings, and keep records accessible through secure cloud backups. Finally, plan for the possibility that cash, contractors, and new credit may be harder to access after a storm.
Make time for a conversation with your insurance professional and, when appropriate, your financial adviser before the season gets busy. A little paperwork now can make it easier to explain a loss, protect your options, and focus on your family when recovery begins.